The Bank of Canada rate October 2025 announcement delivered a 0.25% cut, bringing the overnight lending rate down to 2.25%. This change marks another step in the Bank’s gradual easing cycle

Dated: November 14 2025
Views: 67
The Bank of Canada rate October 2025 announcement delivered a 0.25% cut, bringing the overnight lending rate down to 2.25%. This change marks another step in the Bank’s gradual easing cycle and is already making an impact on mortgage rates, home affordability, and buyer sentiment.
For Vaughan and GTA homeowners, the new rate could slightly reduce variable payments and improve qualifying conditions for upcoming renewals and new purchases.
TL;DR (fast facts)
BoC policy rate: 2.25% (-0.25%)
This is the kind of home that adapts to your needs. Whether you’re growing a family, hybrid working, or just want a bit more elbow room — it ticks all the right boxes.
What changed—and why it matters
The Bank of Canada lowered the policy rate by 25 bps to 2.25%, setting the Bank Rate at 2.50% and deposit rate at 2.20%. The Bank signalled cuts are nearing an end unless the outlook shifts.
Context: headline CPI 2.4% in September (core still above 2%), GDP contracted −1.6% in Q2, unemployment around 7%, and tariff frictions easing at the margin.
Prime Rate Trends
Canada’s key lending rates have both trended downward since mid-2024. The Bank of Canada’s policy rate dropped from 4.75 % to 2.25 %, while major banks’ prime rate followed from 6.95 % to 4.45 %.
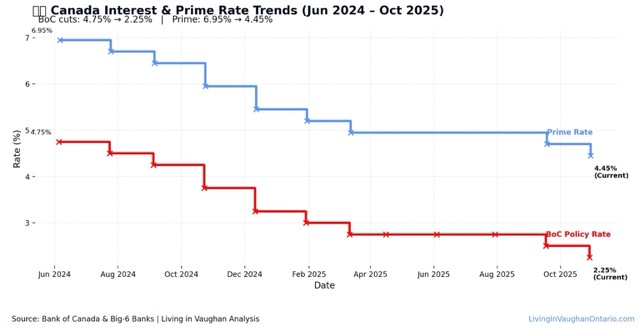
The narrowing gap shows how central-bank moves ripple directly into mortgage and credit costs across the GTA
Who actually benefits (and who doesn’t)
With the Bank of Canada interest rate October 2025 now at 2.25%, variable-rate borrowers will notice immediate relief: anyone with variable-rate mortgages, HELOCs, or variable business loans (they’re priced off prime).
Big lenders moved prime to ≈4.45% (TD mortgage prime 4.60%).
How much relief?
Payment change for a 0.25% cut ≈ $15/month per $100k of mortgage (25–30-year amortization).
Examples:
(Back-of-napkin aligns with amortization math; not advice—ask your broker for your exact numbers.)
Who may not feel it yet
Fixed-rate borrowers: Your rate follows 5-year GoC bond yields. Those yields hovered ~2.6 2.75% around the announcement; if they dip, lenders may trim fixed rates—but bond moves, not BoC, drive that.
Groceries & essentials: Policy rate tweaks demand, not supply. Food prices track supply chains more than BoC moves.
What’s next for Vaughan & GTA real estate?
This Bank of Canada rate October 2025 update is part of a broader easing trend that began earlier this year
Buyers: Slightly better affordability for variables; pre-approvals may stretch a touch farther. Watch bond yields for fixed-rate quotes
Sellers: Lower rates can nudge showings up in rate-sensitive segments (towns/condos, entry detached). Pricing still needs to reflect local comps & inventory.
Investors: Cap rates and debt costs are inching closer; underwriting still needs conservative rents/vacancy.
Renewals (2025–2026): If you’re within 6–12 months, compare blend-and-extend vs. switch vs. shorter terms. A broker can model total interest & penalties.
Smart next steps (no fluff)
READY FOR A NO-PRESSURE PLAN?
Book a call – Take advantage of this Bank of Canada rate October 2025 update
I’ll introduce you to my mortgage broker to provide custom / specific comps that matter to YOU!
As the Bank of Canada rate October 2025 continues to guide mortgage trends, staying informed can help buyers and sellers plan smarter.
Sources (key links)
A marketing focused tech savvy realtor using 17+ years of property buying, selling, and investing journey to create magical real estate experiences for all clients. Everyday, I focus on exceeding cli....
The Bank of Canada rate October 2025 announcement delivered a 0.25% cut, bringing the overnight lending rate down to 2.25%. This change marks another step in the Bank’s gradual easing cycle
On this Jan 1st, I wish you the best of health, happiness, and success in all your personal or professional goals.Writing down your motivation as a positive affirmation and reciting it
All November housing market trends remain on a downward trajectory, similar to the last few months. Vaughan and overall GTA Real Estate market show a continued decline in overall listings
Vaughan and overall GTA Real Estate market show continued decline in overall listings in October 2022 while the home prices seem to be levelling off.With further interest rate increase(s) expected,
 Toronto Real Estate Board (TRREB); All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested
in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than REMAX Experts may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 19, 2026 10:47 AM UTC
Show More...
 All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than REMAX Experts may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 19, 2026 11:14 AM UTC
Show More...